Fixed Indexed Annuities
Fixed indexed annuities combine insurance-company guarantees with an interest-crediting method linked in part to the performance of a market index. Understanding how caps, participation rates, spreads, surrender periods and guarantees work is essential before purchasing one.
What is a fixed indexed annuity?
A fixed indexed annuity is an insurance contract designed to provide tax-deferred accumulation while linking some interest-crediting potential to the performance of a specified index.
Rather than owning the stocks contained in the index, the contract uses an interest-crediting formula established by the insurance company.
The contract may also offer a traditional fixed-interest option in addition to indexed-crediting strategies.
How interest is credited
Cap
A cap places a maximum on the index-linked interest that may be credited for a particular period.
Participation Rate
A participation rate determines what percentage of an applicable index gain is used when calculating interest.
Spread
A spread or margin may subtract a stated percentage from an index gain before interest is credited.
Assume an indexed strategy has a 70% participation rate and the applicable index rises 10% during the measurement period. A simplified calculation could produce a 7% credited rate before considering any other contract provisions. This is only an illustration. Actual crediting methods differ by insurer and contract.
What happens when the index declines?
Fixed indexed annuities generally do not credit a negative interest rate solely because the referenced index declines during a crediting period.
However, this does not mean the contract is completely free of risk or potential reductions in value. Surrender charges, withdrawals, market value adjustments, rider charges or other contract provisions may affect the amount an owner receives.
Insurance guarantees are also dependent on the claims-paying ability of the issuing insurer.
Potential advantages
- Protection from negative index credits under the contract's terms.
- Potential for interest linked to market-index performance.
- Tax-deferred accumulation.
- Optional guaranteed-income features may be available.
- Death-benefit provisions may be available.
- Can complement other retirement-income sources.
Important limitations and risks
Upside may be limited
The return of an indexed annuity generally will not equal the full return of the referenced stock-market index. Caps, participation rates, spreads and other contract provisions can limit credited interest.
Liquidity can be restricted
Many fixed indexed annuities have surrender periods. Withdrawals beyond contractual allowances may result in surrender charges or other adjustments.
Crediting terms may change
Certain caps, participation rates or other terms may be reset by the insurer for future crediting periods, subject to contract guarantees.
Inflation remains a risk
Preserving nominal principal does not necessarily preserve purchasing power. Inflation can reduce the real value of future retirement assets and income.
Insurer financial strength matters
Contractual guarantees depend on the claims-paying ability of the issuing insurance company.
Fixed indexed annuity vs. RILA
| Feature | Fixed Indexed Annuity | Registered Index-Linked Annuity |
|---|---|---|
| Index-linked growth potential | Yes | Yes |
| Negative index credit | Generally no under standard index-crediting terms | Possible |
| Upside limits | Often | Often |
| Downside structure | Insurance-contract guarantees | Often buffers or floors |
| Surrender period may apply | Yes | Yes |
| Security registered with SEC | Generally no | Yes |
For a detailed explanation of the other structure, read the RILA guide.
Fees and costs
Some fixed indexed annuities do not charge an explicit annual base-contract fee, but that does not mean the product has no economic cost.
The insurer may limit credited returns through caps, participation rates, spreads or other contract provisions. Optional riders may also carry additional charges.
Surrender charges can apply when more than the permitted amount is withdrawn during the surrender period.
Tax considerations
Earnings inside a nonqualified annuity generally accumulate tax deferred. Tax is generally due when taxable earnings are distributed, and those earnings are generally taxed as ordinary income rather than capital gains.
Certain taxable distributions taken before age 59½ may also be subject to an additional federal tax. Different rules apply to qualified retirement assets.
Individual tax circumstances differ, so tax questions should be reviewed with a qualified tax professional.
Who might consider a fixed indexed annuity?
A fixed indexed annuity may be considered by someone with a long-term time horizon who places a high priority on limiting direct market-loss exposure while retaining some potential for index-linked interest.
It may also be considered when an investor wants to allocate part of a retirement portfolio to insurance-company guarantees while maintaining other assets for liquidity and longer-term market growth.
When a fixed indexed annuity may not be appropriate
A fixed indexed annuity may not be appropriate when an investor requires substantial short-term liquidity, wants unrestricted stock-market upside, has a short time horizon, or does not understand the contract's surrender provisions and crediting formulas.
Replacing an existing annuity should also be evaluated carefully because a replacement may restart a surrender period or result in the loss of existing benefits.
Questions to ask before purchasing
- How long is the surrender period?
- How much can be withdrawn annually without surrender charges?
- What index or indexes are used?
- What is the current cap?
- What is the current participation rate?
- Does a spread or margin apply?
- Can these terms change in future periods?
- What guaranteed minimums are stated in the contract?
- Are there optional rider charges?
- Is a market value adjustment applicable?
- What happens upon death?
- What alternatives were considered?
- How does the annuity fit into the rest of the retirement portfolio?
Fixed indexed annuities and firefighter retirement
Firefighters and other public-safety employees may retire with pension income, DROP proceeds, governmental 457(b) assets and other savings.
Because a pension may already provide significant guaranteed lifetime income, the role of an additional insurance product should be evaluated in the context of the retiree's entire financial picture.
Liquidity, tax treatment, investment exposure, survivor needs and existing guaranteed income should all be considered before allocating retirement assets.
Start with the complete annuity guide, compare registered index-linked annuities, or review governmental 457(b) planning.
About the author
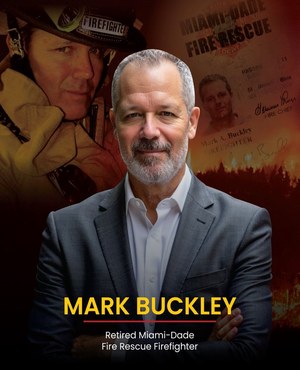
Mark Buckley is a retired Miami-Dade Fire Rescue firefighter and paramedic, author of Beyond The Firehouse, and a financial professional with Prudential Advisors. His educational work focuses on retirement topics affecting firefighters, first responders and retirees.
This material is provided for general educational and informational purposes only and is not intended as individualized investment, insurance, tax or legal advice. Fixed indexed annuity contracts vary significantly in crediting methods, rates, surrender provisions, withdrawal features, riders and guarantees.
Guarantees are subject to the claims-paying ability of the issuing insurance company. Contract terms should be reviewed carefully before purchasing or replacing an annuity.