Annuities Explained
Annuities can play several different roles in retirement planning, but they are not interchangeable and they are not appropriate for every investor. Understanding guarantees, market exposure, fees, liquidity, surrender periods, taxation and downside risk is essential before making a decision.
What is an annuity?
An annuity is a contract issued by an insurance company. Depending on the contract, it may be designed to accumulate money, provide retirement income, offer market-linked growth potential, or combine several of these objectives.
Annuities are commonly used as part of a broader retirement strategy rather than as a replacement for every other type of investment or savings account.
Major types of annuities
Fixed Annuities
Fixed annuities generally credit a stated or contractually determined interest rate. Guarantees depend on the claims-paying ability of the issuing insurance company.
Fixed Indexed Annuities
Fixed indexed annuities credit interest using formulas tied to the performance of a market index. The contract does not directly invest in the index. Caps, participation rates and other crediting features may limit upside.
Variable Annuities
Variable annuities offer investment options whose values fluctuate with market performance. Account value can decline and fees may include mortality and expense charges, administrative expenses and investment expenses.
Registered Index-Linked Annuities
Registered index-linked annuities, sometimes called RILAs, provide index-linked return potential with defined levels of downside protection such as a buffer or floor. Investors can still experience losses depending on contract terms and market performance.
Learn more about Registered Index-Linked Annuities (RILAs) →
Potential reasons retirees consider annuities
- Creating a contractual retirement-income stream.
- Reducing dependence on portfolio withdrawals during market downturns.
- Seeking tax-deferred accumulation within a nonqualified annuity.
- Obtaining a defined level of downside protection in certain contracts.
- Adding insurance-company guarantees to part of a retirement strategy.
- Creating diversification among different retirement-income sources.
Important risks and tradeoffs
Liquidity
Many annuities contain surrender periods or withdrawal limitations. Investors who may need substantial short-term access to their money should pay particular attention to these provisions.
Fees and expenses
Fees vary substantially by contract. Some annuities may have explicit annual charges, investment expenses, rider fees or surrender charges. Other products compensate the insurer through contract design rather than a separately stated advisory fee.
Market risk
Variable annuities and registered index-linked annuities can lose value. A buffer or floor limits certain losses but does not necessarily eliminate downside risk.
Inflation risk
A fixed income payment may lose purchasing power over time if it does not increase with inflation.
Insurance-company risk
Insurance guarantees are subject to the financial strength and claims-paying ability of the issuing insurer.
Tax considerations
Nonqualified annuities generally provide tax-deferred growth. Taxes are generally due when taxable earnings are distributed, and those earnings are typically taxed as ordinary income. Different rules apply to qualified retirement assets.
Certain distributions taken before age 59½ may also be subject to an additional federal tax. Tax treatment depends on individual circumstances, contract structure and applicable law. Investors should consult a qualified tax professional regarding their specific situation.
When an annuity may not be appropriate
An annuity may be a poor fit when an investor needs unrestricted liquidity, has a very short investment horizon, does not understand the contract's limitations, or already has sufficient guaranteed retirement income and has other priorities for the assets.
It may also be inappropriate to exchange an existing annuity simply because a newer contract appears more attractive. Surrender charges, replacement costs, lost guarantees and a new surrender period should all be considered.
Questions to ask before buying an annuity
- What is the primary objective of this contract?
- How long is the surrender period?
- How much money can be withdrawn each year without surrender charges?
- What fees or contract expenses apply?
- Can the account lose money?
- What happens during a major market decline?
- Are caps, participation rates or buffers subject to change?
- What income guarantees are contractual and which are not?
- How strong is the issuing insurance company?
- What are the tax consequences of withdrawals or exchanges?
- How does the annuity fit with Social Security, pensions and other investments?
- What alternatives should also be considered?
Annuities and retirement planning for firefighters
Firefighters and other public-safety employees often retire with financial circumstances that differ from those of private-sector workers. Pension benefits, DROP proceeds, governmental 457(b) plans, early retirement ages and Social Security eligibility can all affect how retirement income should be structured.
For that reason, an annuity decision should not be made in isolation. It should be evaluated alongside pension elections, DROP distributions, 457(b) assets, emergency reserves, insurance coverage and long-term investment needs.
Related resources: 457(b) retirement planning, pension options, and the firefighter retirement guide.
About the author
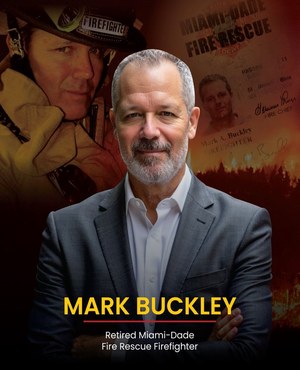
Mark Buckley is a retired Miami-Dade Fire Rescue firefighter and paramedic, author of Beyond The Firehouse, and a financial professional with Prudential Advisors. His educational work focuses on retirement issues affecting firefighters, first responders and other retirees.
This material is provided for general educational and informational purposes only and is not intended as individualized investment, insurance, tax or legal advice. Annuity products differ significantly in features, costs, risks, surrender provisions and guarantees. Investors should review the applicable prospectus or contract and consider their objectives, financial circumstances, liquidity needs and risk tolerance before purchasing an annuity.