Firefighter Retirement Planning: Pensions, 457(b)s, Social Security, Medicare & Life After the Firehouse
Firefighters often retire earlier than workers in many other professions, and public-safety retirement systems can involve pensions, governmental 457(b) plans, DROP programs, Social Security, healthcare decisions and retirement-account distribution choices. This national guide explains the major issues firefighters should understand before their final shift.
The decisions are connected.
A firefighter's retirement is rarely one decision. Pension elections, retirement accounts, healthcare, Social Security, taxes and survivor planning can affect one another. Looking at them together can provide a clearer picture than evaluating each account separately.
1. Pension
Understand benefit calculations, survivor elections, payment options and which decisions may become permanent at retirement.
2. Governmental 457(b)
Understand contribution, distribution, rollover and early-access rules before automatically moving the account somewhere else.
3. DROP
If your retirement system offers a Deferred Retirement Option Program, understand entry rules, accumulation rules, termination dates and distribution choices.
4. Social Security
Review your current Social Security estimate and understand claiming-age, spousal and survivor considerations.
5. Healthcare & Medicare
Plan for employer coverage, retiree coverage, the pre-Medicare period and Medicare enrollment timing.
6. Retirement Income
Determine how pensions, Social Security, retirement accounts, savings and other resources may work together to support spending.
Start planning before the retirement paperwork arrives
The final year of a firefighter's career can involve pension paperwork, accumulated leave, DROP decisions, insurance changes, beneficiary elections and decisions about retirement accounts.
Some choices can be difficult—or impossible—to reverse later. Beginning the review several years before retirement gives firefighters more time to understand their options rather than making several major financial decisions at once.
1. Understand your pension election
Defined-benefit pension systems commonly calculate retirement benefits using factors such as years of service, compensation history, retirement age or service classification. The exact formula is determined by the individual pension system.
Retirement elections may also affect survivor benefits. A higher monthly benefit payable only for the retiree's lifetime may have a very different effect on a spouse or family than a joint or survivor option.
2. A governmental 457(b) can have unusual early-access advantages
Governmental 457(b) plans are common among firefighters, police officers and other state and local government employees.
One important federal tax distinction is that distributions from an eligible state or local governmental 457(b) plan generally are not subject to the 10% additional federal tax on early distributions. However, amounts that entered the 457(b) through a rollover from certain other retirement plans or IRAs can be treated differently.
That means a firefighter retiring well before age 59½ should understand the consequences before automatically rolling an entire governmental 457(b) balance into an IRA.
Source: Internal Revenue Service — Exceptions to Tax on Early Distributions
This does not mean a distribution is necessarily tax-free. Traditional pre-tax distributions are generally included in taxable income unless another rule applies. The distinction discussed here concerns the separate additional early-distribution tax.
3. DROP rules are local—not national
Deferred Retirement Option Programs, commonly called DROP programs, exist in a number of public retirement systems, but there is no single national DROP rule for firefighters.
Eligibility requirements, participation periods, interest or investment treatment, pension calculations and distribution options can vary by retirement system.
A firefighter should therefore use information from the actual pension plan or retirement system rather than assuming another department's DROP rules apply.
4. Social Security changed significantly for public employees
For decades, some public employees who received pensions from work that was not covered by Social Security were affected by the Windfall Elimination Provision (WEP) or Government Pension Offset (GPO).
The Social Security Fairness Act repealed WEP and GPO. According to the Social Security Administration, those provisions no longer apply to Social Security benefits payable for January 2024 and later.
Source: Social Security Administration — Government Pensions and Social Security
Firefighters who previously based their retirement projections on a WEP or GPO reduction should obtain a current Social Security estimate rather than relying on an older projection.
5. Retiring from the fire service and qualifying for Medicare are separate events
Many firefighters retire before Medicare eligibility and therefore need a strategy for health coverage between retirement and Medicare.
Medicare states that the normal Initial Enrollment Period generally begins three months before the month a person turns 65, includes the birthday month and continues for three months afterward—a seven-month period.
Source: Medicare.gov — When Medicare Coverage Starts
Employer coverage, retiree coverage and eligibility for a Special Enrollment Period can affect an individual's situation. Firefighters approaching age 65 should verify their enrollment requirements instead of assuming retiree insurance automatically substitutes for Medicare enrollment rules.
6. A rollover is a decision—not an automatic next step
Retirement frequently triggers conversations about moving money from an employer retirement plan to an IRA or another retirement account.
A rollover may make sense in some circumstances, but it should be evaluated rather than treated as automatic.
Consider investment choices, expenses, services, access to funds, withdrawal rules, creditor protections, beneficiary provisions, consolidation and tax consequences.
7. Build the retirement paycheck before the salary stops
Accumulating assets and generating retirement income are different problems.
A firefighter may enter retirement with several potential income sources: pension benefits, Social Security, governmental 457(b) distributions, IRAs, other employer plans, savings and investment accounts.
The planning question is not simply, "How much money do I have?"
It is also: "How much income will I need, where will that income come from, how flexible does it need to be, and what happens if retirement lasts longer or costs more than expected?"
8. Review beneficiaries before leaving the job
Retirement accounts, pension survivor elections and insurance policies may transfer assets according to beneficiary designations rather than instructions contained in a will.
Marriage, divorce, births, deaths and other family changes are reasons to review beneficiary information before retirement.
Estate, tax and legal questions can become complex, so appropriate attorneys and tax professionals should be consulted when needed.
Questions firefighters should ask before retirement
Looking for Florida FRS information?
Beyond The Firehouse also maintains dedicated educational resources for Florida Retirement System members, including Special Risk firefighters, FRS DROP and related retirement decisions.
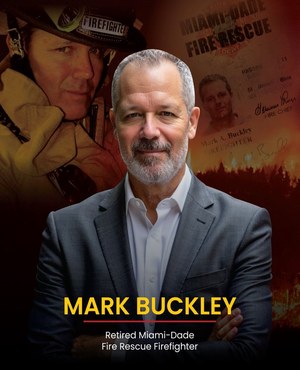
Mark Buckley
Mark Buckley is a retired Miami-Dade Fire Rescue firefighter and paramedic, author of Beyond the Firehouse, and a Financial Professional with Prudential Advisors.
His educational work focuses on retirement issues affecting firefighters and other first responders, including pensions, DROP programs, governmental 457(b) plans, Social Security, Medicare and retirement-income decisions.
Verify important retirement rules at the source.
Retirement, tax and healthcare rules change. These government resources provide additional information regarding several of the federal rules discussed on this page.
- Internal Revenue Service — Exceptions to Tax on Early Distributions
- Internal Revenue Service — Topic 558: Additional Tax on Early Distributions
- Social Security Administration — Government and Foreign Pensions
- Social Security Administration — Social Security Fairness Act
- Medicare.gov — When Medicare Coverage Starts