Annuity Fees, Costs & Surrender Charges
The cost of an annuity depends heavily on the type of contract. Some annuities have explicit annual fees. Others — including some fixed indexed annuities — may have no explicit annual base-contract fee. Understanding the difference between a fee, a surrender charge and an economic tradeoff is critical when comparing retirement products.
Can an indexed annuity really have no annual fee?
Yes. Some fixed indexed annuities are designed without an explicit annual base-contract fee.
In those contracts, an owner may not see an annual percentage deducted from the contract value simply for owning the base annuity.
This can be an important distinction when comparing a fixed indexed annuity with products such as certain variable annuities or managed investment accounts that may have explicit annual charges.
However, an annuity without an explicit annual base-contract fee may still have other costs, restrictions or economic tradeoffs. These can include surrender charges, market value adjustments, charges for optional riders, or limitations on index-linked interest through caps, participation rates, spreads or other crediting methods.
The exact contract — not simply the product category — determines the actual fees, restrictions and benefits.
Fee vs. cost: they are not always the same thing
A fee is generally an amount explicitly charged or deducted from a contract or account.
An economic cost can be broader. For example, an indexed annuity may not charge an annual base-contract fee but may limit the amount of index gain that can be credited.
Explicit Fee
A stated charge deducted from the contract, such as an annual rider fee, administrative fee or mortality-and-expense charge.
Withdrawal Cost
A surrender charge or other contractual adjustment triggered by withdrawing money under specified circumstances.
Economic Tradeoff
A contractual feature such as a cap, participation rate or spread that affects how much interest can be credited.
Surrender charges
Many deferred annuities contain a surrender period. During that period, withdrawals exceeding the contract's permitted amount may be subject to a surrender charge.
Surrender charges often decline over time until they eventually reach zero. The exact schedule differs among contracts.
Assume an annuity allows a certain amount to be withdrawn without a surrender charge, but an owner takes substantially more than that amount during the surrender period. The amount above the permitted withdrawal could be subject to a surrender charge according to the contract's schedule. The actual percentage and calculation depend on the specific contract.
A surrender charge should not automatically be viewed as an annual fee. It is generally a contractual withdrawal charge that applies under specified conditions.
Free-withdrawal provisions
Many annuity contracts permit some access to contract value without triggering the normal surrender charge.
The amount may be determined as a percentage of contract value, premium, accumulated value or another formula specified by the contract.
The phrase “free withdrawal” generally means free from the annuity's surrender charge. It does not necessarily mean the distribution is free from income tax, tax penalties or other contract consequences.
Market Value Adjustments
Some annuity contracts include a Market Value Adjustment, commonly called an MVA.
Depending on interest-rate movements and the terms of the contract, an MVA may increase or decrease the amount available when certain withdrawals or surrenders occur during a specified period.
An MVA is different from an annual management fee and should be evaluated separately when considering liquidity.
Optional rider fees
Some annuities offer optional benefits for an additional charge.
Examples can include:
- Guaranteed lifetime withdrawal benefits
- Enhanced death benefits
- Income riders
- Long-term-care-related features
- Other contractual benefit riders
A base annuity may have no explicit annual contract fee while an optional rider attached to that same contract carries an annual charge.
That is why both the base contract and any optional riders should be reviewed separately.
How fixed indexed annuity costs may work
Some fixed indexed annuities may not impose an explicit annual base-contract fee.
Instead, the insurer determines how index-linked interest is credited through contractual features such as:
- Caps
- Participation rates
- Spreads or margins
- Specified crediting methods
- Declared rates
These provisions affect the return credited to the contract and may change for future crediting periods within the limits established by the contract.
For a complete explanation, read the Fixed Indexed Annuity Guide .
RILA fees and economic tradeoffs
Registered index-linked annuities can use combinations of caps, participation rates, buffers, floors and other formulas.
Some contracts may have explicit charges, while others may primarily reflect economic costs through the terms governing upside participation and downside exposure.
Because RILAs can expose investors to losses, their cost should not be evaluated solely by looking at stated fees.
Learn more in the RILA education guide.
Variable annuity expenses
Variable annuities often have a different expense structure from fixed indexed annuities.
Potential expenses may include:
- Mortality and expense risk charges
- Administrative expenses
- Underlying investment-option expenses
- Optional rider charges
- Surrender charges
- Other contract-specific expenses
Investors should review the prospectus and contract carefully because fees can vary substantially among products and share classes.
Annuity costs compared with managed accounts
| Consideration | Fixed Indexed Annuity | RILA | Variable Annuity | Managed Investment Account |
|---|---|---|---|---|
| Explicit annual base fee | May be none, depending on contract | Depends on contract | Often present | Often present |
| Investment advisory fee | Generally not a base-contract charge | Depends on arrangement | Depends on arrangement | Common |
| Surrender charge | May apply | May apply | May apply | Typically not an annuity surrender charge |
| Optional rider charge | May apply | May apply | May apply | Generally not applicable in the same form |
| Underlying investment expenses | Generally not structured as mutual-fund subaccounts | Depends on contract | Common | Fund or ETF expenses may apply |
| Upside limitations | Often | Often | Generally investment driven | Generally investment driven |
| Liquidity restrictions | Can be significant | Can be significant | Can be significant | Usually more liquid, depending on holdings |
What about commissions?
Compensation can differ depending on the annuity, distribution arrangement and financial professional involved.
In some commission-based annuity transactions, compensation to the financial professional is paid by the issuing or distributing company rather than being shown as a separate annual deduction from the owner's contract value.
That does not mean compensation is irrelevant. Investors should understand how the financial professional is compensated and whether alternative products or compensation arrangements were considered.
Tax considerations
Nonqualified annuity earnings generally grow tax deferred until distributed.
Taxable annuity distributions are generally subject to ordinary-income tax rules rather than long-term capital-gains rates.
In addition, certain taxable distributions made before age 59½ may be subject to an additional federal tax unless an exception applies.
Qualified retirement accounts and governmental retirement plans may operate under different distribution and tax rules.
Tax treatment depends on individual circumstances, and tax questions should be reviewed with a qualified tax professional.
The cost of replacing an existing annuity
Replacing one annuity with another should be evaluated carefully.
A replacement may create a new surrender period and can result in the loss of existing guarantees, rider benefits, favorable contract provisions or other features.
Potential advantages of the new contract should therefore be compared with both the direct and indirect costs of giving up the existing contract.
Questions to ask before purchasing an annuity
- Is there an explicit annual base-contract fee?
- If there is no annual fee, how does the insurer limit credited returns?
- Does the contract have a surrender period?
- What is the surrender-charge schedule?
- How much can be withdrawn without a surrender charge?
- Does a Market Value Adjustment apply?
- Are there optional rider charges?
- What are the current cap and participation rates?
- Can those rates change?
- Are there administrative expenses?
- Are there underlying investment expenses?
- How is the financial professional compensated?
- What happens if I need substantial liquidity?
- What happens if I replace this annuity later?
- What non-annuity alternatives were considered?
- How does this contract fit with the rest of my retirement portfolio?
Why the lowest stated fee is not automatically the best choice
Cost matters, but it should not be evaluated in isolation.
A lower-cost product may provide fewer guarantees, less downside protection, different liquidity or less favorable features for a particular investor.
Conversely, paying more for features that an investor does not need can reduce long-term value.
A useful comparison considers cost, liquidity, risk, income needs, guarantees, tax treatment, time horizon and available alternatives together.
Annuity expenses and firefighter retirement planning
Firefighters and other first responders may enter retirement with a pension, DROP proceeds, governmental 457(b) assets and other savings.
Because pension income may already provide a substantial guaranteed-income component, annuity costs and benefits should be evaluated within the retiree's entire financial picture rather than in isolation.
Liquidity, survivor needs, investment exposure, taxes, retirement income and emergency reserves should all be considered.
Continue with the Annuity Education Center, the Fixed Indexed Annuity Guide, the RILA Guide, or our 457(b) Retirement Guide.
Frequently asked questions
Can an indexed annuity have no annual fee?
Yes. Some fixed indexed annuities may have no explicit annual base-contract fee. Other charges, restrictions or economic tradeoffs can still apply depending on the contract.
Does “no annual fee” mean the annuity costs nothing?
No. A contract may still contain surrender charges, rider fees, Market Value Adjustments, withdrawal restrictions or limits on credited interest.
Is a surrender charge an annual fee?
Generally no. A surrender charge is typically triggered by certain withdrawals or termination of the contract during the surrender period.
Do all annuities have the same fees?
No. Expense structures vary significantly among fixed annuities, fixed indexed annuities, RILAs and variable annuities.
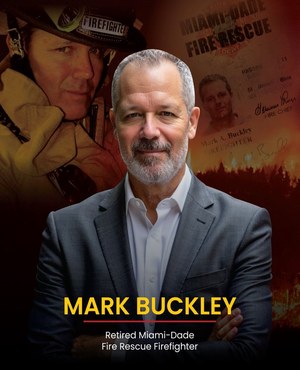
About the author
Mark Buckley is a retired Miami-Dade Fire Rescue firefighter and paramedic, author of Beyond The Firehouse, and a financial professional with Prudential Advisors.
His educational work focuses on retirement planning topics affecting firefighters, first responders and retirees.
Additional educational resources
Readers who want additional information about annuities, fees and taxation may also review educational material from:
This material is provided for general educational and informational purposes only and is not intended as individualized investment, insurance, tax or legal advice.
Annuity contracts vary significantly. Fees, expenses, surrender provisions, withdrawal features, interest-crediting methods, rider charges and guarantees depend on the specific contract and issuing insurance company.
References to products with no explicit annual contract fee should not be interpreted to mean that such products have no costs, restrictions or economic tradeoffs.
Insurance guarantees are subject to the claims-paying ability of the issuing insurance company. Investors should review applicable contracts, prospectuses and disclosure documents before making a purchase or replacement decision.