Why start five years before retirement?
Firefighters spend years preparing for emergencies, promotions and changes in assignment. Retirement deserves the same level of preparation. Waiting until the final few months can create unnecessary pressure at the exact time when pension elections, healthcare decisions, retirement-plan distributions and beneficiary choices may all be arriving at once.
Retirement systems vary significantly by state, municipality and department. The purpose of this checklist is therefore not to tell every firefighter to make the same decision. It is to identify the questions that should be answered before the final shift.
Build the retirement map
- Request an updated pension estimate from your retirement system.
- Identify available pension survivor and beneficiary options.
- Understand DROP or similar deferred-retirement programs if your system offers one.
- List every retirement account, including governmental 457(b), 401(a), 401(k), 403(b), IRA and Roth accounts.
- Review your Social Security earnings record and estimated benefits.
- Estimate your expected retirement expenses instead of relying only on your current paycheck.
- Review outstanding mortgage, auto, credit-card and other debt.
- Begin building a cash reserve for the transition into retirement.
Test the numbers
- Compare estimated pension income with anticipated monthly expenses.
- Estimate how much additional income may need to come from retirement accounts or other sources.
- Review how your 457(b) or other employer plan can be accessed after separation.
- Determine whether unused leave, DROP proceeds or other lump sums may be payable at retirement.
- Review life insurance and survivor-income needs.
- Verify beneficiary designations on pensions, retirement accounts and insurance policies.
- Consider how taxes may change when wages are replaced by pension and retirement income.
Turn estimates into decisions
- Request current pension and retirement-plan documents rather than relying on old estimates.
- Confirm your intended retirement date and required separation paperwork.
- Review pension payment and survivor elections carefully.
- Decide how much accessible cash you want available during the first year of retirement.
- Compare the features of your employer retirement plan with any rollover alternatives before moving money.
- Review Social Security claiming choices based on your individual circumstances.
- Determine how health coverage will work after retirement and before Medicare eligibility, if applicable.
Confirm the transition
- Confirm pension paperwork and payment dates with the retirement system.
- Verify when employer health coverage ends.
- Confirm direct-deposit and tax-withholding instructions.
- Know when any DROP, leave payout or retirement-plan distribution becomes available.
- Make sure beneficiary information is current.
- Keep copies of retirement forms, benefit elections and plan statements.
- Avoid making a large rollover simply because retirement paperwork has arrived.
Manage retirement as a new financial phase
- Track pension, Social Security and retirement-account income against actual expenses.
- Review tax withholding after several months of retirement income.
- Maintain an appropriate emergency reserve.
- Review investment risk based on your new income needs and time horizon.
- Revisit beneficiaries and estate documents after major family or financial changes.
- Review the retirement plan at least annually rather than treating the retirement date as the finish line.
Governmental 457(b) plans deserve special attention
Many firefighters participate in governmental 457(b) deferred-compensation plans. Under current federal tax rules, distributions from an eligible governmental 457(b) plan generally are not subject to the federal 10% additional tax on early distributions. Amounts rolled into the 457(b) from certain other types of retirement plans can be treated differently.
This is one reason firefighters should understand what they own before automatically moving retirement assets after separation. A rollover can change plan features, investment choices, fees, services and future withdrawal rules.
Read more: Firefighter early-retirement withdrawal rules and leaving a governmental 457(b) versus rolling it to an IRA .
Social Security should be part of the retirement-income decision
Social Security retirement benefits can generally begin as early as age 62, but the age at which benefits begin affects the monthly amount. The decision should be considered together with pension income, retirement savings, employment plans, family circumstances and expected income needs rather than viewed in isolation.
Do not wait until 65 to think about Medicare
Medicare's Initial Enrollment Period generally lasts seven months, beginning three months before the month a person turns 65 and ending three months after the birthday month. Firefighters who retire before 65 should also determine how health coverage will be maintained between retirement and Medicare eligibility.
People covered by an employer health plan after 65 may have different enrollment considerations, so Medicare timing should be reviewed before employer coverage ends.
The biggest mistake may be waiting
Retirement decisions often become concentrated into the final months of a career. Starting several years earlier creates time to understand the options, correct beneficiary information, reduce unnecessary debt, organize accounts and evaluate major decisions before retirement becomes an administrative deadline.
A simple five-year firefighter retirement checklist
- Know your pension estimate.
- Know your survivor options.
- Understand your DROP program if one applies.
- Know what retirement accounts you own.
- Understand the withdrawal rules for each account.
- Review your Social Security record and claiming options.
- Plan for healthcare before and after Medicare eligibility.
- Review beneficiaries and estate documents.
- Estimate your retirement expenses.
- Build a retirement cash reserve.
- Review debt before the paycheck stops.
- Understand tax withholding on retirement income.
- Compare options before making a rollover or other irreversible decision.
Related firefighter retirement guides
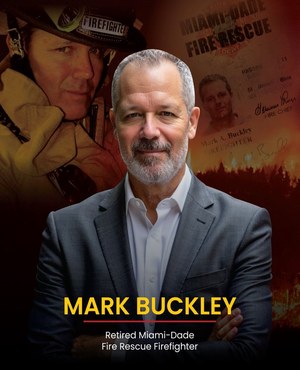
About Mark Buckley
Mark Buckley is a retired Miami-Dade Fire Rescue firefighter and paramedic, author of Beyond the Firehouse, and a Financial Professional whose educational work focuses on retirement issues affecting firefighters and first responders.
Official Sources
- Internal Revenue Service — Retirement Topics: Exceptions to Tax on Early Distributions
- Internal Revenue Service — Topic No. 558: Additional Tax on Early Distributions
- Social Security Administration — Retirement Benefits and When to Start Receiving Benefits
- Medicare.gov — Initial Enrollment Period and Medicare Coverage Start Dates
Educational information only. This material provides general educational information and is not individualized investment, tax or legal advice. Retirement plans, pension systems and benefit rules vary by employer and jurisdiction. Consult your plan administrator and appropriate financial, tax and legal professionals regarding your individual circumstances.
Securities offered through LPL Enterprise (LPLE), Member FINRA/SIPC, and an affiliate of LPL Financial. Prudential Advisors is a brand name of The Prudential Insurance Company of America and its related entities.